
A £450,000 three-bed house near the North Circular rarely looks exciting on paper. This one earns a 5.0% gross yield and a 5.9% equity IRR. Those numbers alone would send most investors to the next listing.
The interior tells a different story. Dark wood panelling covers the walls and ceilings. The kitchen, bathroom and carpets date from another era. Our model calls it a classic renovator's dream: sound structure, total cosmetic overhaul needed.
We ran the rent, the comparables and the refurbishment numbers. Here is what we found, including two details the listing does not mention.
Overall assessment
3 bedroom property for sale in North Circular Road, Neasden, London, NW2
For SaleTorquity gives this house a composite score of 41 and an appeal score of 3.8 out of 10. The low scores reflect the dated interior. The fundamentals hold up better.
The asking price works out at £5,293 per m². The house sits on a 100 m² plot with a private rear garden, a shed and off-street parking. A driveway matters here. It adds real value for tenants on a road this busy.
The financing model uses an interest-only loan of about £240,000 at roughly 4.75%. Equity invested comes to £253,846, covering the deposit and purchase costs. Year-one cash flow reaches £427 a month. That gives a 2.02% cash-on-cash return and a 1.45x DSCR.
The 10-year projection assumes rent grows 3.5% a year and the property value grows 3% a year. Rental cash flow adds up to about £80,000 over the hold. Price growth adds another £155,000 on paper. Most of the return depends on the London market rising, so investors should test a flat-price scenario before they commit.
Rent Estimates
Rent Estimates
Based on 10 comparablesOur model estimates rent at £1,885 a month, or £22.18 per m². Confidence sits at medium, with a range of £1,313 to £2,458. The model also builds in a 5% void, so year-one income comes to £21,489.
The estimate looks cautious. Every comparable lets for more per square metre, from £23.50 to £35.70. Four-bed houses nearby average about £25 per m². At that rate, this house would rent for roughly £2,150 in its current state.
The low figure probably reflects the condition. Tenants pay less for dark panelling and an old bathroom. A landlord who lets it as is should expect the lower half of the range.
Financial Projection
Financial Projection
10-year holdThe model runs a 10-year hold with an interest-only loan of £239,800. That covers 53% of the price at an implied rate of about 4.75%. Annual debt service stays flat at £11,390. The buyer puts in £253,846, which covers a £210,200 deposit plus about £43,600 in purchase costs.
Year one looks thin. Rent brings in £21,489 after a 5% void allowance. Operating costs take £4,973, or 23% of income. Net operating income reaches £16,516, and £5,126 remains after the mortgage. That works out at £427 a month.
The picture improves with time. The model grows rent 3.5% a year, so monthly cash flow climbs to about £930 by year ten. Net operating income rises to £22,549. Cumulative cash flow over the hold comes to roughly £80,000.
The base case delivers £171,165 in total profit and a 5.91% equity IRR. Rental cash flow accounts for about £80,000 of that. The rest comes from the exit. The model grows the property value 3% a year, from £450,000 to about £605,000. After selling costs and the recovery of purchase costs, that adds roughly £91,000.
Two stress tests show where the risk sits. Hold the price flat for ten years, and total profit falls to around £21,500. The IRR drops below 1%. Raise the mortgage rate to 5.75%, and year-one cash flow shrinks to about £2,700. The DSCR falls to 1.20x, close to the limit many lenders accept.
The interest-only structure keeps monthly payments low but builds no equity through debt paydown. Every pound of capital gain depends on the market. The live renovation scenario lifts the IRR to 7.39%, and it carries the same dependence on price growth.
Our reading: the projection works as a long-term hold in a rising London market. It offers little protection if prices stall or rates climb. Investors should run the flat-price scenario in Torquity before they make an offer.
Comparable Properties
Comparable Properties
10 foundThe model found 10 rentals within 1 km, at an average distance of 760 m. The average match score sits at 29%, which tells you the local market offers few true peers.
None of the comparables has three bedrooms. Five are two-bed flats from 49 to 68 m², letting for £1,750 to £2,100. Four are four-bed houses from 138 to 164 m², letting for £3,500 to £4,100. The closest match is a four-bed on North Circular Road itself, at 100 m² for £2,600.
That last comparable deserves attention. It sits on the same road, has a similar footprint and lets for £2,600. It suggests the road itself does not cap rents as hard as many investors fear.
Two entries need caution. One Shearwater Drive flat appears twice, at £3,684 and £2,100. The higher figure looks like an outlier, and we would exclude it. Brook Road and Vincent Gardens also share almost identical coordinates and rents.
Renovation Analyser
Renovation Analysis
6 rooms scoredOur renovation model rates this property 9 out of 10 for upside. It projects a 45% rent uplift after a £47,400 refurbishment. That would take rent to about £2,735 a month.
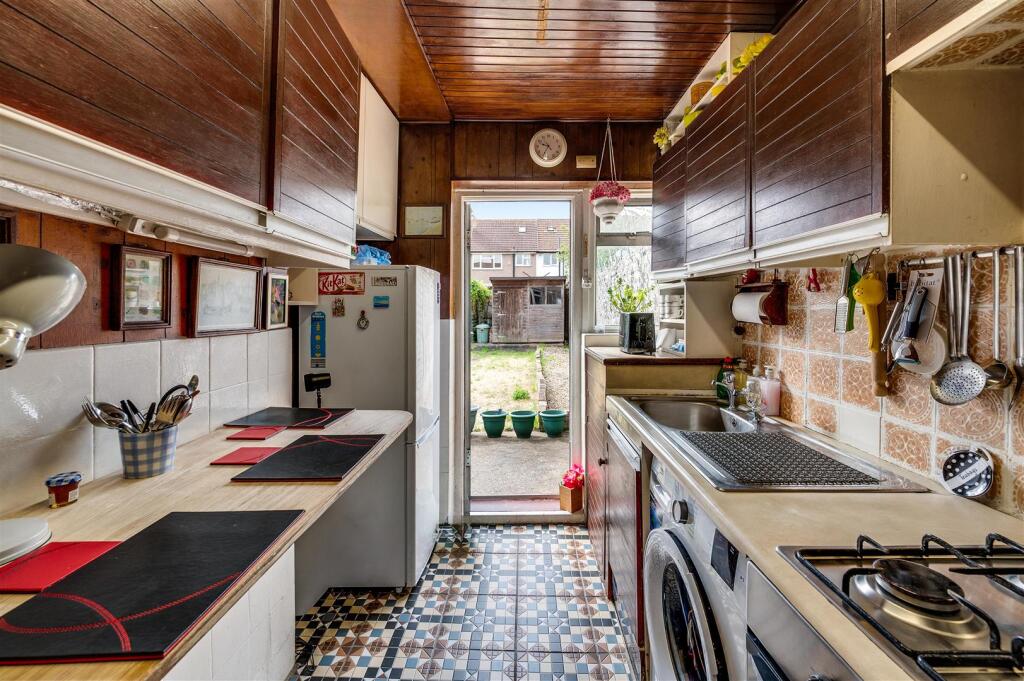
 Before
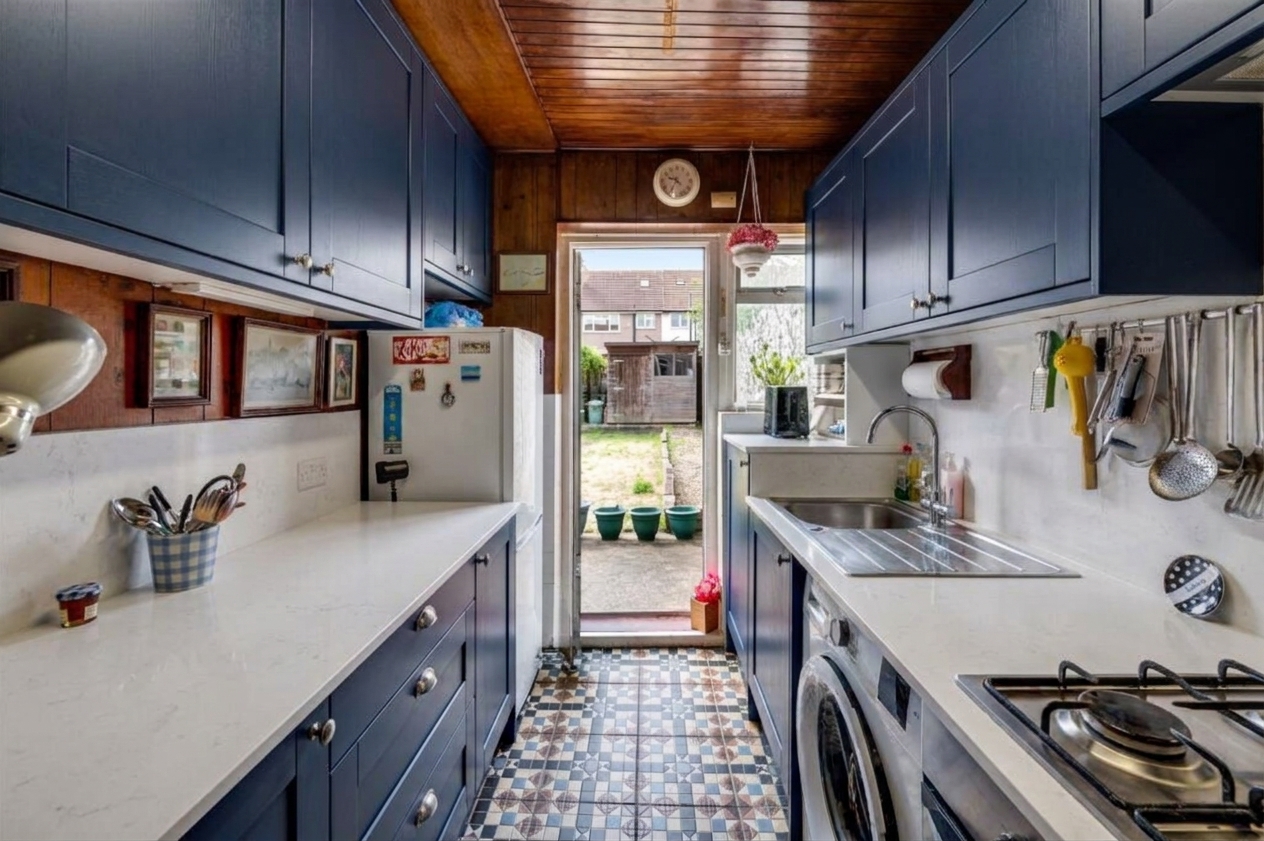
After
Kitchen — Complete kitchen overhaul with shaker-style cabinetry and quartz worktops (£14,500)
Our renovation model scores this property 9/10 for upside, projecting a 45% rent uplift after refurbishment.
- KitchenComplete kitchen overhaul with shaker-style cabinetry and quartz worktops£14,500
- Bedroom 2 · Bedroom 3 · Dining Room · Hallway · Living RoomStrip wood paneling, replaster, and paint walls in neutral off-white£13,500
- BathroomFull bathroom refurbishment including tiling and modern fixtures£7,000
- Bedroom 2 · Bedroom 3 · Dining Room · Hallway · Living Room · Primary BedroomReplace all dated carpets with oak-effect luxury vinyl tile (LVT) flooring£8,500
- Primary BedroomRemove glossy red ceiling panels and paint flat white£600
- Private GardenGarden landscape: re-turf lawn and replace perimeter fencing£3,300
The plan covers four items. A new kitchen with shaker cabinets and quartz worktops costs £14,500. Three reception spaces each get panelling removed, fresh plaster and neutral paint at £13,500 per room.
We see three gaps. First, the listing describes two reception rooms, yet the plan budgets for three. One living room likely appears twice. Second, the plan leaves out the bathroom and the carpets, both flagged as dated. Third, a house with this much original panelling often hides old wiring and heating, so budget a contingency for both.
The uplift also looks ambitious. £2,735 sits above the top of the rent range at £2,458. We would underwrite rent at £2,400 to £2,450 after the works. At £2,450, total cost of £497,400 yields 5.9% gross and lifts year-one cash-on-cash to around 3.3%.
Verdict: is this a good deal?
As a straight buy-to-let, no. A 2% cash return and a 5.9% IRR leave little margin for a rate rise or a long void. Most of the projected profit comes from assumed price growth, which no buyer controls.
As a value-add project, it deserves a viewing. The live renovation scenario lifts equity IRR to 7.39%. A buyer who negotiates the price and controls the refurbishment budget can push that higher.
Hidden gems
- Off-street parking and a private garden on a 100 m² plot
- A cautious rent estimate, below every local comparable per m²
- A four-bed on the same road letting for £2,600
- A sound structure with good natural light in the main rooms
Pitfalls
- The A406 brings noise and pollution that some tenants avoid
- Refurbishment budget skips the bathroom, flooring and likely electrics
- No EPC rating in the data, and rentals need at least an E today, with a proposed rise to C by 2030
- An interest-only loan means no debt paydown, so returns lean on price growth
- The 45% rent uplift sits above the comparable range